At the G20 Summit, Gordon Brown has suggested a Tobin Tax (a tax on financial transactions) to pay for the global bank bailouts and deficits. This came as a massive shock not only to other global leaders, but to all those who have been campaigning for such a tax for several years.
At Prime Minister's questions less than a year ago, Alan Simpson MP suggested a Tobin Tax to "deter speculators from playing the terribly destructive role that they have played in throwing us into the current recession". Brown's response was that a Tobin Tax "has been found by many people who have looked at it not to be implementable".
Just a month before that another Campaign Group MP - Neil Gerrard - was dismissed by Treasury Minister Stephen Timms who said, "The Government have previously studied the technical implications of a proposed tax on sterling currency transactions and reached the view that there would be economic distortions across a range of activities beyond just the foreign exchange markets, the cost of which would be likely to far outweigh the relative costs of raising finance via other mechanisms that Governments use".
No one has yet explained Brown's Damascene conversion. Nevertheless, the severity of the UK's deficit caused the ongoing bank bailouts means that the time is exactly right to consider a tax that could raise billions from the finance sector. Surely logic hasn't reached Brown's thinking?
Showing posts with label G20. Show all posts
Showing posts with label G20. Show all posts
Sunday, 8 November 2009

Tuesday, 22 September 2009
ILO G20 report, and the UK
The ILO has published a report in advance of the G20 summit in Pittsburgh later this week. The report, Protecting people, promoting jobs: A survey of country employment and social protection policy responses to the global economic crisis, compares measures taken by 54 countries in the wake of the global recession. It makes interesting reading.
Apologies for being a bit nationalistic, but here in short is what it shows about the UK:
My favourite graph though is on page 20 of the report about comparable fiscal stimulus packages for 2008-10. Here the UK is well below the average, committing only 1% of GDP, compared with over 1.5% in Denmark, Germany, Finland, Sweden, New Zealand and Spain; and over 2% in Canada, Japan, Australia, the US and South Korea.
Why is it, despite Brown's modest press briefings at the G20 in London, that the UK cannot do more? It might be to do with the massive debt from our dodgy banks which were deregulated under Brown's chancellorship, and bailed out at huge cost under his Premiership.
Apologies for being a bit nationalistic, but here in short is what it shows about the UK:
- UK unemployment is slightly below the G20 average of 8.5%
- However, UK unemployment has risen more quickly in the last year than on average: up 38% here, compared to the average of 29.6%
- We are one of the select few countries where manufacturing has fallen more than 10% in the last year - alongside the US, Spain and Canada
- Of the countries that have had similar declines in GDP to the UK (i.e. more than 4%) only Spain has also had such a "sharp" increase in unemployment. Germany, Italy and Japan have all managed to stop job losses rising so quickly with comparable GDP drops.
My favourite graph though is on page 20 of the report about comparable fiscal stimulus packages for 2008-10. Here the UK is well below the average, committing only 1% of GDP, compared with over 1.5% in Denmark, Germany, Finland, Sweden, New Zealand and Spain; and over 2% in Canada, Japan, Australia, the US and South Korea.
Why is it, despite Brown's modest press briefings at the G20 in London, that the UK cannot do more? It might be to do with the massive debt from our dodgy banks which were deregulated under Brown's chancellorship, and bailed out at huge cost under his Premiership.
Thursday, 9 April 2009
'Creative destruction' order of the day
Despite the G20’s attempts at confidence-boosting rhetoric, the interdependent components of the global economy remain locked in a deadly embrace, wrestling with each other as they plummet to the ground.
Ever more desperate attempts to resuscitate the fantastic but failed world of credit and debt dilute the value of currencies and further worsen the health of the global corporations as demand falls for the goods they produce, sending their share prices down.
In Britain, all talk of a “recovery” later this year has disappeared and next week’s Budget is in fact a crisis measure as public finances spiral out of control. European steel production is close to collapse and a trade war with China is looming over its dumping strategy.
The Irish government is the first to admit in practice that neither additional government borrowing, nor expanding the supply of money can help its country withstand the impact of the global crisis of dwindling production and consumption. It won’t be the last.
In measures designed to forestall the looming threat of state bankruptcy, its emergency second budget looks like the flailing autotomised arms of a threatened octopus, when a limb is severed by the endangered creature.
In a so far maverick response to the shock forecast that economic activity in the Republic is forecast to shrink by 8% this year, a dramatic worsening of last year’s 3% contraction, finance minister Brian Lenihan warned of "a serious decline in national living standards: the sharpest fall on record.”
Taxes will rise, though not on corporate profits, and spending on services will be slashed. In the public sector pay will be hard hit affecting a large part of the population.
Nevertheless, with already the worst government deficit in Europe, and the entire financial sector in a state of collapse, a new Irish agency will be provided with funds to buy up the banks’ property and land-based bad debt. The catch here is that no-one knows what its real value is, nor what the price should be.
Elsewhere in Europe, rather than taking the route of printing money to add to the trillions already given or promised to the banks, Germany and France have been giving away vouchers in a new-for-old car scrapping scheme.
Demand for Germany’s €2,500 vouchers has been hugely successful. Far more people have applied than expected, and concern is rising about the public anger that will erupt when the money runs out. Angela Merkel’s surprised government has added a further €3.5bn taking the total available to €5bn.
Sales of brand new small cars have soared, but there’s a catch here too – it doesn’t seem to have increased consumption overall. The second hand market has collapsed completely and what spending there is, is transferring from other products like TVs and sofas.
As the crisis enters historically uncharted territory, governments are exhausting all the weapons they can use in their attempts to rescue the capitalist way of life. The Irish pioneers have opened the doors to a new phase.
Joseph Schumpeter, an economist high priest of capitalist business cycles, and an opponent of Keynes, described the process in his famous book, Capitalism, Socialism and Democracy, when he wrote: “This process of Creative Destruction is the essential fact about capitalism. It is what capitalism consists in and what every capitalist concern has got to live in.”
Gerry Gold
Economics editor
A World to Win
http://www.aworldtowin.net/
Friday, 3 April 2009
G20: The IMF consolation prize isn't enough

Graham Turner (Graham will be speaking at the LEAP Conference 'Capitalism Isn't Working' on 25th April)
In the end, Brown and Obama could not get the Europeans to agree on yet another fiscal boost at the G20 meeting. But the consolation prize – an infusion of $500bn into IMF coffers – gave the Anglo Saxon leaders something to trumpet.
Their brand of casino capitalism may have spawned multiple credit bubbles across a wide swathe of emerging market economies. But as eastern Europe and many other countries slide towards depression, their governments can rest assured. The global cop of last resort, the IMF, will come to the rescue.
Many will shudder at the thought. When the SE Asian bubble burst in 1997, IMF staffers were sent to Bangkok, Seoul, Kuala Lumpur and Jakarta to impose tough conditions for loans that still failed to prevent exchange rates from collapsing.
In return for emergency loans, they demanded a draconian and anti-Keynesian tightening of fiscal policy that drove the Asian economies deeper into recession.
We wait to see if similar terms and conditions will be applied today. Judging from the myriad bailouts launched by the IMF since last year, nothing has changed since 1997. It is still one rule for the west, another for the rest.
Indeed, it was the IMF intervention in 1997 that persuaded central banks across developing countries never to be left so dependent upon the west again. They vowed to drive their foreign exchange reserves higher, to provide a cushion against financial crises. But that merely aggravated trade imbalances and provided the fuel for the global credit bubble of 2004-2008.
When it all came crashing down, record reserves were still unable to cushion these countries from the incompetence of western governments.
And trebling the IMF's kitty will not resolve the core immediate problem facing the world economy – a collapsing US housing market. Ironically, the Bank of England's rapid fire rate cuts are gaining traction, with some signs of a stabiliation in the UK housing market.
Obama can only dream. The US took the world into recession, and it may take many countries into depression yet. The collapse of the US housing market is accelerating because, for ideological reasons, the Obama administration will not nationalise its banks and intervene to stabilise its housing market. Obama's plans are little different from those seen in the final months of the Bush administration.
February saw a record decline in house prices across 20 major US cities, because banks are unable and unwilling to pass on rate cuts to homeowners. Average property values are now 30% below their peak, but they could easily fall that far again.
Unemployment in the US is soaring. March could be the worst month yet for job losses, as the wider "U6" unemployment rate, including discouraged and involuntary part-time workers, soars to 20% and beyond.
One in eight homeowners with a mortgage will have been in arrears or in default by the end of March. That could climb to one in seven or one in six over the summer. Obama is not facing up to the scale of economic and social catastrophe facing his country.
And not even a bigger IMF will be able to fix that.
Wednesday, 1 April 2009
G20: My message to the alternative summit
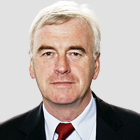
John McDonnell MP
Bankers banking their bonuses, MPs fiddling their expenses, ex-ministers lining their pockets with consultancies, and the prime minister in denial about his role in creating this cesspit of greed and corruption. For most of us, what else is there to do but get out on the streets to protest and resist?
Political representation isn't working.
Democracy within the political party that was founded to transform our society has been largely closed down. Political representation within it for an alternative vision of the world has increasingly been squeezed out by internal constitutional manoeuvres and manipulated selection processes, which have now even moved on to parachuting the progeny of the New Labour hierarchy into safe seats.
Within parliament, patronage has reduced the commons chamber to a rubberstamping ritual of obsequiousness, where virtually a two-day week has evolved and where vast swathes of new laws are forced through on a guillotine without even a debate.
No10 and the government departments are populated with advisers either coming from, or going to, lucrative posts in big business. The decision over Heathrow expansion exemplifies the style of policy-making that starts with capitulation to a powerful self-interested lobby, blatantly fixes a public consultation and then drives through a policy that destroys any vestiges of green credentials the government had left.
Hardly surprising, then, that people are taking to the streets and direct action. Climate campers camping, sacked workers occupying, Heathrow villagers at vigils and peace promoters marching.
Do the so-called world leaders sitting at the summit table realise the depth of anger that is brewing up in communities across the world? Maybe, but it seems not yet as they limit their horizon to minimal reform to salvage a system that has brutalised our society and plundered our planet for profit.
Between most of them they have turned the world economy into a casino, while, for most of us, to quote Morales, "We're not willing to play anymore." The solutions required to this latest crisis of capitalism have gone beyond fiscal stimuli, bank bailouts and quantitative easing. Stabilising a system so that the next generation experiences another similar crisis in 20 years, as time continues to run out for the planet, is increasingly exposed as pointless.
Spinning a summit communiqué to create an image of co-ordinated decision-making for the home country electorate just won't wash as firms close, unemployment mounts and poverty grows across the globe. The principles underlying the signs of real change that are needed to come from this summit are hardly new:
• Democratic rights at the core of every institution and every decision
• Labour rights firmly established and enforced by organisation and mobilisation
• Equality established practically by the redistribution of wealth and power founded upon common ownership, global tax justice and fair trade
• Survival ensured by a real sense of urgency in tackling climate change by concerted and decisive global action
• Peace secured by commitment to conflict prevention and resolution underpinned by disarmament and the end of the arms trade
If the summit could only make a start in setting this agenda there might be some hope. If it doesn't, the need for mass protest and direct action will prove to be not just justified but necessary.
This article originally appeared on Comment is Free
Getting it right about Marx
Mounting street-level opposition to the capitalist G20 governments London gathering prompted the Evening Standard to observe this week that the impact of the combined financial and economic crises is making Karl Marx’s analysis of capitalist society attractive to a rapidly increasing number of people looking for explanations and solutions.
With a pretence of balance the ES wheeled out two writers to present the case for and against Marx. Francis Wheen, author of Marx's Das Kapital, which tells the story of the 20-year struggle to complete his seminal analysis of capitalism, is in the red corner. Wheen, to his credit, draws attention to Marx’s profound analysis of the underlying capitalist profit-seeking alternating but worsening cycle of growth, overproduction, bust, and destruction and its mutually-dependent relation with credit and debt.
But to use Wheen as Marx’s defender is a deliberate trap for the unwary. As we have shown elsewhere, Wheen’s real mission is to undermine Marx by reducing him from a revolutionary to an acute observer, saying: “Marx's vivid portrayal of the forces that govern our lives will never lose its resonance, or its power to bring the world into focus.” Calling on financier George Soros, for help, Wheen shows that Marx was right about the inherent instability of the system but can’t resist adding: “The fall of the bourgeoisie and the victory of the proletariat have not come to pass.”
In the blue corner, defending capital, is Emma Duncan deputy editor of The Economist claiming that “the central idea in Marxism – that the interests of the workers and owners were separate and opposed – is no longer true”. Her facile argument is that anyone who has a pension or life insurance “owns part of the means of production because the pension funds and life insurance companies are the biggest owners of shares in companies in the world”. Astoundingly she concludes that as a result, the class war “which Marx thought would bring the system down is over”.
Despite Duncan, the two social, class forces set in opposition to each other by capitalist society continue to express themselves. Peter Brabeck, the head of Nestlé, the world’s largest food company, and vice-chairman of Credit Suisse, said yesterday that the company is confident that it can weather the general decline in global consumption. In the developed, rich, overstuffed countries with a mounting proportion of obese adults and children, quantitative limits of “caloric input” have been reached and are giving way to quality. But it’s OK for Nestlé. They are so big that they cover every aspect of the business, and will make their profits from whatever food people buy. And, even better, based on current projections, world population is predicted to rise from 6.5 billion to 9 billion – more mouths to fill with profitable (if sometimes dangerous) food products! Nestle owns the Chinese company that was lacing children’s milk with poison last year.
The global trade union body ITUC published its own broad-based assessment of the food crisis on the same day. It shows how investors fled from the credit crisis last year, transferring their funds to speculate on commodity futures. This has resulted in higher prices, putting even subsistence foods beyond the reach of many. As a result 150 million more people have been driven to and beyond the brink of starvation. Global estimates put the number facing acute hunger at over 1 billion.
So much for the alleged identity of interests of workers and capitalists that Duncan muses about. As to Wheen’s passive, one-sided, non-revolutionary view of Marx, we should simply repeat what Marx himself wrote in his Theses On Feuerbach in 1845: “Philosophers have hitherto only interpreted the world in various ways; the point is to change it.”
Gerry Gold
Economics editor
www.aworldtowin.net
1 April 2009
Sunday, 16 November 2008
We need a new world economic order
John McDonnell MP
(This article first appeared on Guardian Comment is Free on Friday)
Barack Obama has decided not to attend the G20 summit convened by George Bush and the lack of involvement by India, China and the developing world in the G7 means that the best we can hope for is that this Saturday's talks are a preparatory session for a more inclusive and wider ranging summit in the New Year.
The timing is just not right to secure anything more than limited agreement on coordinating measures to mitigate the recession – and to set an agenda for the post-inaugural economic summit it is hoped the new president will convene.
Brown and Sarkozy will vie with each other over the weekend for the title of saviour of the global economy, but the reality is that until Obama is installed in the White House and unless China and India are engaged, little will change.
In the meantime, millions of workers worldwide will lose their jobs and homes as the recession bites. Many more people in the developing world will be pushed over the edge of poverty into destitution, with starvation putting many lives at risk. The demand for change, which elected the first black president of the US, has the potential to grow into a demand for change in the system that produces such insecurity and suffering.
Civil society now has a part to play in this transitional period between the G20 meeting and what appears to be the inevitable emergence of a new global institutional settlement that reflects the new world economic order.
Since the post-war world's economic institutions (the World Bank, IMF and WTO) were captured by neo-liberals in the 1970s, they have proved themselves a major part of the problem, not the solution to global economic instability. The same policies that have brought individual national economies to their knees are the policies that these institutions have spread across the globe. They have produced the global crisis.
The globalisation of unrestrained free market, rapacious capitalism by this economic institutional structure has produced inequality and insecurity in the west, desperate poverty in the developing world and a sequence of brutal wars causing immense human suffering. The plundering for profit of the world's natural resources has threatened the very sustainability of the planet.
A new democratically accountable architecture of global economic co-operation is now needed – new institutions pursuing new policies.
Civil society organisations could help set this transformation agenda to focus the minds of the politicians in the same way the popular demand for change after the experience of the 1930s depression created the Bretton Woods settlement. In our own lifetime the Jubilee 2000 campaign forced third world debt onto the global agenda.
An agenda of basic demands from any new global civil society coalition could include:
• A new structure of global economic governance inclusive of China and India and a wider representation of the developing world.
• The establishment of a democratically elected global assembly to scrutinise the policies and operation of the new global economic institution.
• The tackling of destabilising market speculation, through the introduction of a Tobin tax on international currency speculation.
• An end to trade policies and the imposition of trade agreements which are tied to deregulation, liberalisation and the privatisation of public services.
• An end to the policy of global collusion in the operation of tax havens that allow rich individuals and transnational corporations to avoid fair taxation.
• A renewed commitment to achieving the Millennium Development Goals, recognising the productive stimulus this would give the world economy in recession.
• An agreement that every nation signs up to the International Labour Organisation (ILO) conventions on international labour standards so that workers have the basic protections needed as recession sweeps the globe.
With this type of programme we could wrest the process of globalisation from the control of the corporations. The risk of the individual country recessions slipping into a worldwide depression provides the stimulus and the opportunity to create a new world economic order.
Friday, 14 November 2008
Can we do it? Yes we must!
As the political leaders of 20 of the biggest economies gather in Washington to work out how to fix the global capitalist economy as, like a runaway train, it heads straight for the buffers, the range of "solutions" is piling up. None of them have a hope of taking off.
For outgoing US President George Bush, the oh-so-obvious answer is "sustained economic growth". He told a New York audience that "the answer is not to try to reinvent that system" but to "make the reforms we need, and move forward with the free-market principles that have delivered prosperity and hope to people around the world".
Others are into reinvention. Gordon Brown, who until recently thought globalised capitalism could not possibly be improved upon, is now for "creating a new global financial architecture" to replace the Bretton Woods monetary system (which actually collapsed 40 years ago!). The Germans want a "new balance between market and state" while the Canadian suggestion is that "dynamic new economic players ... must be full participants at the global table".
There’s another proposal aired by Bob Geldof. He is back banging the drum for Africa, which has been left out of the discussions. Bob wants to ensure that "900 million potential producers and consumers" are drawn into "the next round of globalisation". With the whole world diving into slump, Bob sees salvation for capitalism in Africa.
And on that he’s at one with Bush, who just yesterday received a major humanitarian award from Africare for his work in Africa. No really, it’s true.
According to Voice of America White House correspondent Paula Wolfson, Bush was honoured for his efforts throughout his administration to combat disease across the continent. Bush says America has an obligation to help the people of Africa. "It is in our national security interest that we defeat hopelessness. It is in our economic interest that we help economies grow."
The brutal truth is all these plans, pleas and proposals are non-starters. Why? Because they all look beyond the current disastrous disintegration of the global economy to a bright, newly refurbished, much more regulated, fairer, capitalist world. This is not how capitalist slumps work themselves out.
Fixing the real problem - an overhang of capacity as global production turns from recession to depression and slump - has only one solution as far as capitalism is concerned. In 1942 in the midst of the Second World War, economist Joseph Schumpeter, a critic of Keynes, but a big fan of credit-led investment, published his most famous work Capitalism, Socialism and Democracy. It was then, with the world at war, that he chose to develop his version of the concept of "creative destruction". That is already under way, with 10 million Americans already out of work and General Motors on the edge of bankruptcy.
Bush bemoaned the fact that critics were "equating the free enterprise system with greed, exploitation and failure" and objected to it. He is right to warn against the coming assault on the citadels of capitalism. There’ll be many demonstrations and protests against the G20 over the weekend and the election of Obama last week was itself a product of the anger millions of Americans who want action against bankers and corporations.
What is urgently needed is a concept of a society beyond the private ownership and control of capital, together with the leadership and organisation to make it a reality.
Can we do it? Yes we must!
Gerry Gold
Economics editor
A World to Win
http://www.aworldtowin.net
Subscribe to:
Posts (Atom)